

Venmo
by Venmo
4.0
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.0
- Price
- Free
- Download
- 50.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I approached Venmo as a first-time user would: not looking for a complicated financial system, but for a practical way to send or receive money without turning a simple favor into a long conversation about bank details. It is a free finance app from Venmo, rated for Everyone, and its appeal is easy to understand once you use it for a real shared expense. The main experience is built around paying people, requesting money, and keeping track of those exchanges in one place.
My overall impression is positive, especially for people who regularly split meals, household costs, gifts, or small personal expenses with friends and relatives. The app feels more natural for person-to-person payments than for full banking. That distinction matters. I would recommend it to someone who wants a familiar payment routine, but I would not treat it as a replacement for a bank account, a budgeting app, or every payment method already in a person’s life.
From installation to a useful first payment
I’d make the first payment a low-stakes one tied to a specific shared expense, then check that both people can identify it in their activity. That gives me a practical way to learn the confirmation flow without relying on memory or rushing through a larger settlement. Once that feels straightforward, the next section looks at the setup choices that help make routine use clearer.
What to expect before you begin
Venmo has been available since May 17, 2010, and its long presence is reflected in how recognizable the service has become. The Android listing shows more than 50 million installs, with an average rating of 4.0 from roughly 909 thousand ratings and about 357 thousand written reviews. Those figures do not guarantee that every experience will be smooth, but they do show that this is an established app rather than a niche experiment.
The current Android version is 26.12.0, and it requires Android 8.0 or later. The app is free to install. Before downloading, I would still check that the phone has a supported operating system and that the person you intend to pay can be found through the service. A payment app is only useful when the people involved can actually complete the same workflow.
The first thing I noticed is that Venmo is designed around recognizable people and specific payment moments. “I owe you for dinner” is a better starting point than “I need a complete financial dashboard.” That focus keeps the basic action approachable, although it also means users expecting detailed money management may find the experience narrower than they hoped.
Setting up an account without rushing
For a new user, the best approach is to install the app and move through the account setup carefully rather than tapping through every screen as quickly as possible. Use a name and contact details that your friends will recognize, because the hardest part of a payment is often choosing the correct person. A familiar profile makes that decision less stressful than searching through several similar names.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also recommend deciding in advance how you want to use the service. If your goal is to split occasional expenses, keep the account focused on that purpose. If you expect frequent payments, think about which contacts you will use most and how you want to label transactions. A little consistency at the beginning makes the activity history much easier to understand later.
Security deserves attention during setup. Use a strong account password and keep your phone protected with its normal screen lock. I would not treat a payment app like a casual social app simply because its interface feels friendly. Before confirming any transaction, check the recipient, amount, and note. That pause is more valuable than trying to fix a mistake afterward.
One subtle point for beginners is that a successful account setup does not automatically mean every payment path will feel identical. Sending money, receiving money, and moving money onward can involve different choices and different expectations. I would first complete a small, familiar transaction with someone I trust instead of making the first attempt during an urgent purchase or a complicated group event.
Your first meaningful success
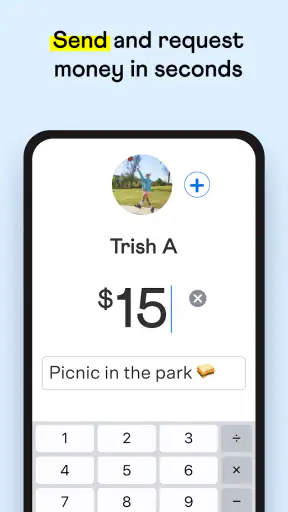
The clearest first test is a simple request or payment connected to something you can identify immediately. Imagine sharing lunch with a friend. Rather than opening a calculator later and trying to remember the exact amount, you can create the payment around that meal, add a short note, and send or request the amount while the context is still fresh. The note is not decoration; it helps both people recognize why the transaction exists.
Before submitting, I would review the recipient’s identity and the amount twice. If the app presents more than one possible contact, do not rely only on a profile picture or a familiar first name. Confirm the full identity using the conversation you already have with that person. This is one of the most practical habits a new user can develop, because a fast interface can make an incorrect selection feel deceptively easy.
A good first success is not merely seeing a confirmation screen. It is being able to answer three questions afterward: who was paid, what the payment was for, and whether the other person understood the amount. If those answers are clear, the app has done its job. If the transaction is confusing even when the amount is small, that is a sign to slow down before using it for rent, travel costs, or a large group expense.
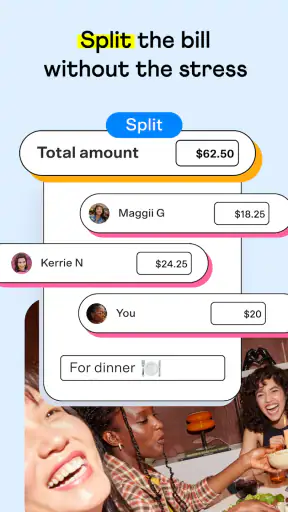
For shared purchases, I find the request workflow particularly useful. One person can cover the bill, then ask the others for their portions while the event is still easy to remember. This avoids the common problem of sending several vague messages such as “Can you send me your part?” The important improvement is not just speed; it is giving the payment a clear purpose that can be recognized later.
Where new users commonly hesitate
The social style can be both the app’s most approachable feature and its most confusing aspect. A payment may look conversational, but it is still a financial action. I would never approve a transaction solely because the message or note sounds familiar. Treat the friendly presentation as a way to organize activity, not as proof that a request is legitimate.
Another source of hesitation is the difference between recording an expense and actually settling it. Writing a note about a dinner does not replace checking whether the money was sent or received. When a group is involved, decide who is paying the restaurant, who is reimbursing that person, and whether everyone is splitting evenly. Venmo can make the exchange easier to track, but it cannot decide a fair split for you.
People also sometimes expect a payment app to behave like a traditional bank. That is where I would set realistic expectations. Venmo is most compelling for direct exchanges between people. Someone who mainly wants a full account overview, long-term savings tools, detailed spending analysis, or a single place for every financial task may prefer a bank’s own app or a dedicated budgeting service.
There is also a practical social limitation: the service works best when the intended recipient is already comfortable using it. If one person prefers bank transfers, another uses a different payment platform, and a third wants to pay in cash, the group may still need a backup plan. I would not make Venmo the only option for an important deadline unless everyone involved has already used it successfully.
Using activity history as a memory aid
One of the less obvious benefits is that a payment history can reduce the mental work of informal accounting. I like the idea of writing specific notes such as “electric bill,” “concert tickets,” or “groceries,” rather than relying on memory. Months later, a precise description is much more useful than a vague label, especially when several payments to the same person appear close together.
This habit is especially helpful for recurring household arrangements. If two roommates alternate purchases, each person can use consistent wording and review the activity before settling up. It is not a substitute for a formal spreadsheet when the amounts become complex, but it is a lightweight record for ordinary shared costs.
For group trips, I would use a simple routine: agree on what is being shared, keep notes tied to the individual expense, and settle in batches instead of sending a stream of tiny payments. Batching reduces clutter and makes it easier to spot a missing contribution. The trade-off is that everyone must remember the same arrangement, so the app works best when the group communicates clearly outside the payment screen.
Privacy, visibility, and personal boundaries
Because the experience has a social flavor, I would pay close attention to who can see transaction details and what you write in a note. Even an innocent description can reveal information about a purchase, location, event, or relationship. My rule is simple: include enough context for the recipient to identify the payment, but avoid unnecessary personal details.
This is also a good reason to separate humor from financial records. A joke may seem harmless at the moment, yet a clear, neutral note is easier to understand later and less likely to create an awkward impression. The best payment history is one that helps you and the other person identify the transaction without exposing more than needed.
I would also be cautious with unexpected requests. If a message claims to be from someone you know, verify it through another conversation before paying. Familiar names and social wording can lower a person’s guard. The app can simplify a legitimate exchange, but common-sense verification remains your responsibility.
How it compares with familiar alternatives
Compared with a bank transfer, Venmo feels more suitable for casual reimbursements. A bank app may be the better choice when you are moving money between accounts you control, handling formal payments, or dealing with someone who does not use Venmo. Banks also tend to be the natural home for broader account management, so switching between the two is often more sensible than forcing one service to do everything.
Compared with cash, the advantage is traceability. You do not need to find exact bills, and a written note can preserve the reason for the exchange. Cash can still be better for very small in-person situations, for people who prefer not to use an app, or when connectivity and account access are uncertain. Venmo’s convenience depends on both sides being ready to use the same digital process.
Compared with other person-to-person payment apps, the deciding factor is usually not a dramatic difference in the basic idea. It is where your friends, family, roommates, or coworkers already are. A technically appealing app is less useful if the people you need to pay are elsewhere. I would choose the service that minimizes friction for the whole group, not just the one with the most attractive interface.
Who should use it and who should skip it
I think Venmo is a strong fit for people who frequently split everyday costs, send reimbursements to friends, request money from family, or want a simple activity trail for informal payments. Students, roommates, couples managing shared purchases, and groups arranging casual events can all benefit from its focused approach.
I would be more cautious about recommending it as someone’s only financial app. If you need detailed budgeting, business-grade bookkeeping, complex bill management, or a complete view of your finances, look at tools designed specifically for those jobs. Likewise, someone who rarely sends digital payments may gain little from installing another service when cash or a bank app already solves the occasional need.
It is also not my first choice for a high-pressure first transaction. Start with a small payment to a known contact, learn the confirmation flow, and only then use it for larger shared expenses. That gradual approach answers the most important beginner question—“Will I understand what happened?”—before the stakes increase.
My next-step routine after the first payment
After completing the first successful exchange, I would create a personal routine rather than simply leaving the app installed. Use clear notes, check the recipient every time, and review unsettled requests before a group event becomes old news. If you share expenses regularly, agree with the other people on whether you will settle after each purchase or once at the end of a week or trip.
I would also keep a separate record for anything important enough to affect a monthly budget. Venmo can make the payment itself convenient, but a payment history is not the same thing as a spending plan. That distinction prevents a common mistake: confusing an organized list of transactions with an understanding of whether you can afford them.
For Android users, the free app supports devices running Android 8.0 or newer, and the Everyone age rating makes it broadly approachable. Still, age suitability does not remove the need for responsible account use. A younger or inexperienced user should understand that sending money is a real financial decision, not merely another chat interaction.
After spending time with it, I see Venmo as a focused tool with a friendly surface and a practical core. Its best moments are ordinary ones: settling lunch, sharing a household purchase, or requesting a clearly labeled contribution without chasing someone through messages. Its weaknesses appear when users expect full banking features, skip identity checks, or involve people who do not share the same payment habits.
My recommendation is to start small, write useful notes, and treat every confirmation as a financial record. If your everyday problem is informal payments between people you already know, Venmo can make that routine noticeably cleaner. If your needs extend into comprehensive money management or formal transfers, keep it as one tool among others rather than making it the center of your financial life.
Pros
- User-friendly interface makes transactions simple.
- Splits bills easily with friends and family.
- Instant notifications for all transactions.
- Supports multiple payment methods, including credit cards.
- Offers a social feed to track and share expenses.
Cons
- Requires internet connection for transactions.
- Transaction fees for certain payment methods.
- Limited customer support options available.
- Privacy settings can be confusing for new users.
- Not all merchants accept Venmo as payment.
FAQs for Venmo
How does Venmo work, and is it safe to use?
Venmo is a mobile payment service that allows users to transfer money to friends and family quickly and easily. It operates through a social media-like interface where transactions can be shared with your network. Venmo employs encryption to protect your financial information, but users should still take precautions, such as using strong passwords and enabling two-factor authentication.
Are there any fees associated with using Venmo?
Venmo is mostly free for personal transactions when using a linked bank account or debit card. However, if you choose to use a credit card, there is a 3% fee per transaction. Additionally, there are fees for instant transfers to your bank account and certain business transactions, so it’s wise to review these before proceeding.
Can I use Venmo internationally or with international accounts?
Venmo is currently only available in the United States. You can use it to send and receive payments domestically, but international transactions or using Venmo with international bank accounts and cards are not supported at this time. For global payments, you might want to consider other services like PayPal.
What are the social features of Venmo, and can I control my privacy settings?
Venmo allows users to share their transactions on a social feed, similar to social media platforms. You can control who sees your transactions by adjusting your privacy settings. Options include making transactions public, visible to friends only, or private. It’s advisable to review and adjust these settings according to your comfort level.
What should I do if I encounter an issue or unauthorized transaction on Venmo?
If you encounter any issues or unauthorized transactions, you should contact Venmo support immediately through their app or website. They have a dedicated team to handle such situations. It’s also recommended to monitor your account regularly and report discrepancies as soon as possible to ensure timely resolution.

Venmo
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support+android@venmo.com, visit https://venmo.com/, or review their https://venmo.com/info/privacy-policy.










